Data Privacy Notice: Buying or selling an individual’s personal information is illegal — we respect data privacy and never provide, offer or sell personal (individual) data to anyone. Reselling data purchased from us is a punishable offence under Indian Copyright Law.
B2B Companies Data
GST & Registration Data
Industry & Trade Data
City & State Wise Data
Professional & Service Data
International Buyers & Sellers
Exhibitors & Combo Packs
How to Get Sales Data of a Company
Published 2026-09-15
Wanting a read on a specific company’s sales activity is common before a partnership, a vendor onboarding decision or a simple competitive check. The trick is matching the request to a realistic source, since the depth of detail available depends heavily on whether the company is your own or someone else’s.
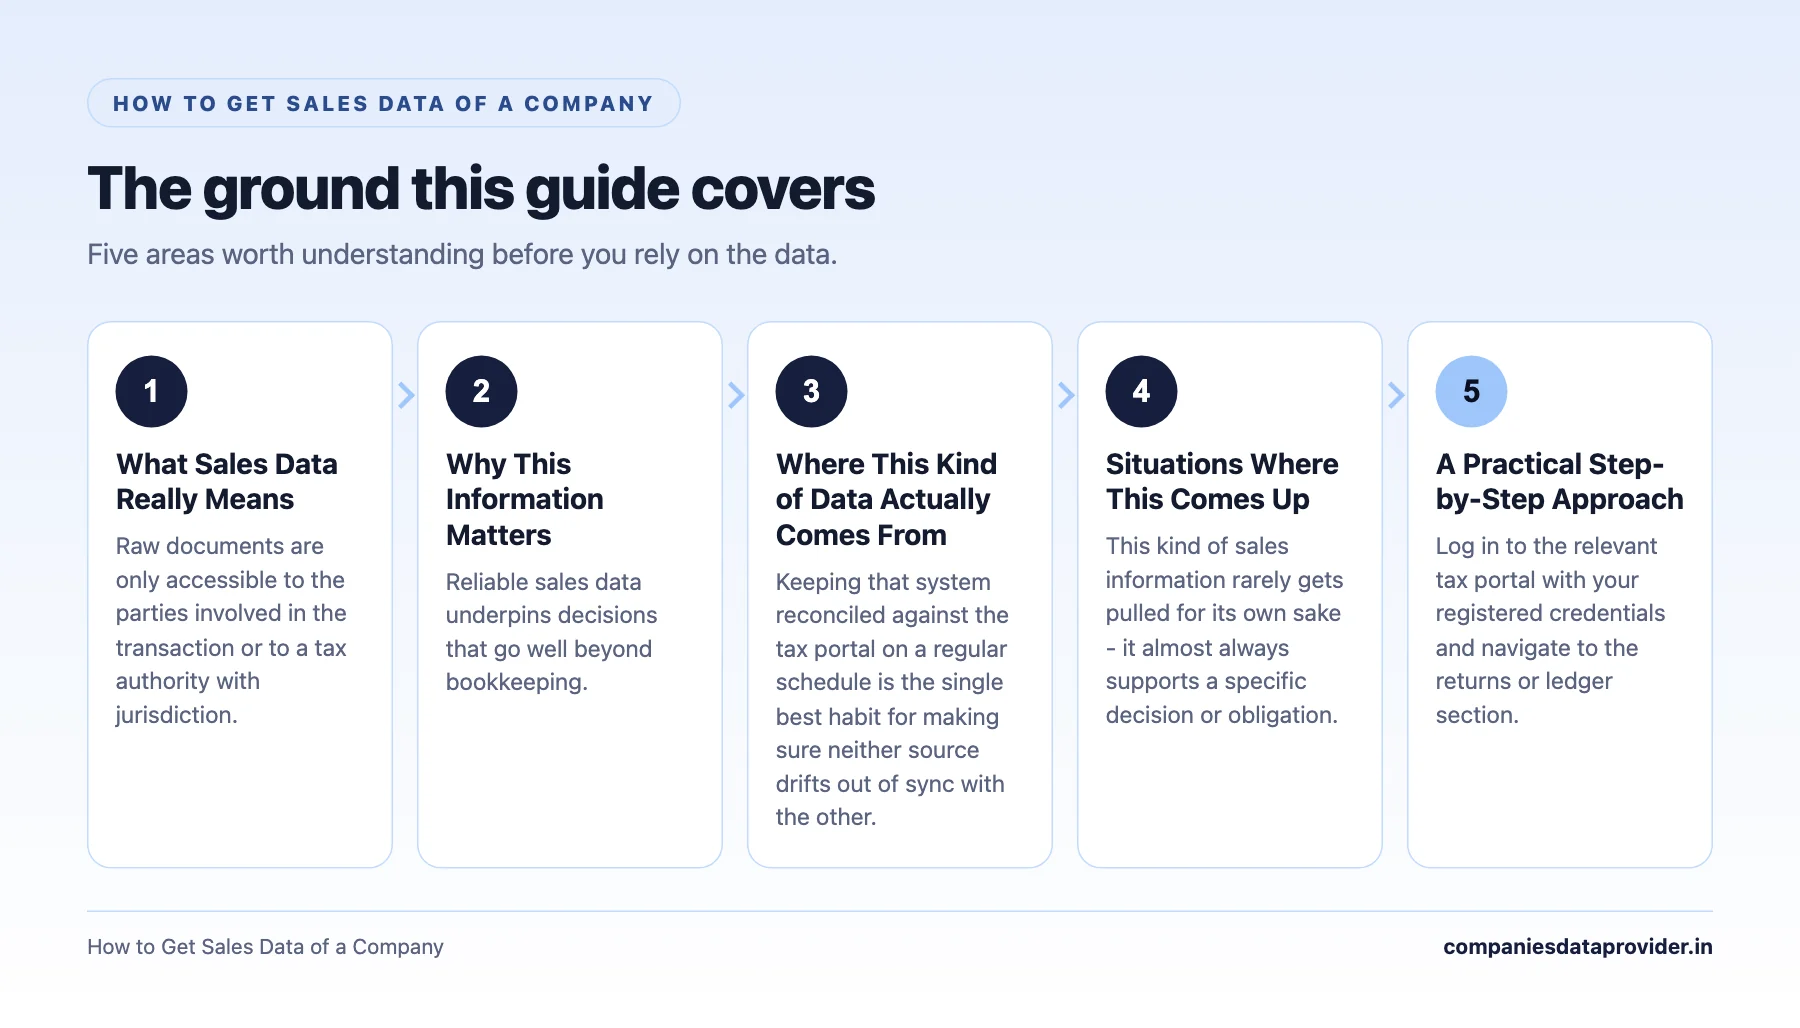
What Sales Data Really Means
Sales data is the record of commercial transactions – who supplied what, to whom, on what date and for what value – captured either as individual documents or as aggregated summaries. When people talk about finding sales data for a specific company, they are usually looking for one of three things: the raw documents themselves, a summarised total for a period, or a qualitative sense of how active and consistent that commercial activity has been over time.
It helps to separate these three needs early, because the route you take to find sales data depends heavily on which one you actually want. Raw documents are only accessible to the parties involved in the transaction or to a tax authority with jurisdiction. Summaries and activity signals, on the other hand, can often be sourced from public filings, tax portals and specialised business data platforms.
Why This Information Matters
Reliable sales data underpins decisions that go well beyond bookkeeping. It feeds tax filings, supports loan and credit applications, informs pricing and inventory decisions, and gives management an honest picture of whether the business is growing, shrinking or simply holding steady. Without it, decisions end up based on memory or gut feeling, which rarely holds up when a lender, auditor or investor asks for evidence.
Good sales records also protect a business during a dispute. If a counterparty questions a payment or a tax authority raises a query, having clean, well-organised records turns a stressful back-and-forth into a quick lookup and a confident answer.
Where This Kind of Data Actually Comes From
For information about other businesses, the realistic sources are public company registries, filed financial statements, industry directories and specialised business data platforms that aggregate publicly available signals into structured profiles. These platforms do not expose anyone’s private transaction ledger; instead they compile registration details, filing history, trade categories and estimated activity levels into a profile that is far more useful than searching one registry at a time.
Internally, a business’s own accounting system is usually the richest source of sales data, since every invoice raised or received typically gets logged there as it happens. Keeping that system reconciled against the tax portal on a regular schedule is the single best habit for making sure neither source drifts out of sync with the other.
Situations Where This Comes Up
This kind of sales information rarely gets pulled for its own sake – it almost always supports a specific decision or obligation. A few common situations illustrate why getting the process right matters.
- Preparing accurate tax filings without last-minute scrambling for missing documents.
- Supporting a loan or credit application with a clear, verifiable activity history.
- Informing pricing, inventory and staffing decisions with real trend data instead of impressions.
- Responding quickly and confidently when a partner, lender or authority asks a specific question about past activity.
A Practical Step-by-Step Approach
- Log in to the relevant tax portal with your registered credentials and navigate to the returns or ledger section.
- Select the period you want sales data for and generate or download the relevant statement.
- Cross-check the downloaded figures against your internal accounting records for the same period.
- Flag and investigate any mismatches before treating the numbers as final.
- Store the reconciled data in a consistent format so it is easy to retrieve the next time you need it.
What to Look for in a Good Source or Process
Not every source of business information is equally trustworthy, and it pays to apply a short checklist before relying on any single number. First, ask how recently the underlying figures were updated – stale data quietly undermines even a well-designed report. Second, ask whether the source explains where its figures come from; a platform or document that shows its working is far more useful than one that simply presents a number with no context.
Third, check whether the sales information can be cross-referenced against at least one independent source. A single data point is a claim; two or more consistent data points from different origins start to look like a fact. Finally, favour tools and processes that let you export or save your findings in a structured format, since a screenshot or a one-time page view is far less useful than a record you can revisit, filter and build on later.

Tips for Keeping the Data Accurate
Consistency beats intensity when it comes to sales records. A short, regular reconciliation habit – say, at the close of every filing period – catches small mismatches while they are still easy to trace, instead of letting them pile up into a confusing backlog. Keep a single naming convention for files and folders so nothing gets duplicated or lost under a slightly different label.
Where you rely on an external source for information about another business, note the date you pulled the figures and the source itself. Business activity changes over time, and a profile that was accurate months ago may no longer reflect current scale. Treating every external figure as time-stamped evidence rather than a permanent fact keeps your own analysis honest.
It also helps to write down the exact steps you followed the first time you complete a search or a reconciliation of this kind. A short, plain-language note – which section of the portal you opened, which filters you applied, which platform you checked – turns a one-off effort into a repeatable procedure that a colleague could follow without needing to ask you directly.
Common Mistakes Worth Avoiding
- Relying on a single stale export instead of refreshing sales data on a regular schedule.
- Mixing figures from different periods without clearly labelling which period each number belongs to.
- Assuming a document is correctly classified without checking who issued it and which direction the payment moved.
- Treating an estimate from a third-party source as if it were an audited, official figure.
- Skipping reconciliation between internal records and the tax portal until a filing deadline forces the issue.
Compliance Considerations Worth Remembering
Records of sales activity are not just internal management tools; they are the evidence base for tax filings and, potentially, for future audits. Keeping them organised, dated and reconciled is as much a compliance obligation as it is good practice. Whenever a figure is corrected, keep a short note of what changed and why, so the trail remains clear if anyone reviews it later.
A Quick Checklist Before You Rely on the Numbers
Before treating any sales figure as final, run through a short set of checks. It takes only a few minutes and catches most of the errors that otherwise surface much later, usually at the worst possible time – during a filing deadline or an external review.
- Confirm the period the figures cover and make sure it matches the period you actually need.
- Confirm the source and, where possible, note the date the figures were last refreshed.
- Reconcile the total against at least one independent record before using it in a report.
- Check for obvious gaps, such as a missing period or a counterparty that appears once and then never again.
- Save the reconciled version in a clearly labelled file so the next person who needs it does not have to repeat the same work.
This habit costs little and pays for itself the first time it prevents a wrong number from reaching a lender, an auditor or a management meeting.
Frequently Asked Questions
Where should I start if I need sales data quickly?
Start with the source closest to the transaction itself – your own accounting system or the tax portal for your own business, and public filings or a business data platform for another business.
How far back can this kind of data usually be retrieved?
It depends on the source’s retention policy, but most portals and accounting systems keep several years of filed history available for export.
Is it safe to rely on a single export without double-checking it?
It is better to reconcile any export against at least one other record before treating it as final, since even routine exports can occasionally miss late entries or corrections.
Bringing It All Together
How to Get Sales Data of a Company does not have to be a mystery once you separate what you are actually trying to learn – raw documents, a summarised total, or a general sense of scale – from where that specific kind of information can legitimately come from. For your own business, the tax portal and your accounting system together give a complete and authoritative picture. For information about other businesses, public filings and specialised business data platforms give a reliable, ethically sourced picture without ever requiring access to anyone’s private records. Building the habit of regular reconciliation, clear labelling and source tracking will make every future search for sales information faster and more trustworthy than the last.
98 Lists Across 7 Groups
Every group below is a live category page with its own lists, pricing and free sample. Pick the one closest to your market and drill in.
Talk To Us About A Custom Pull